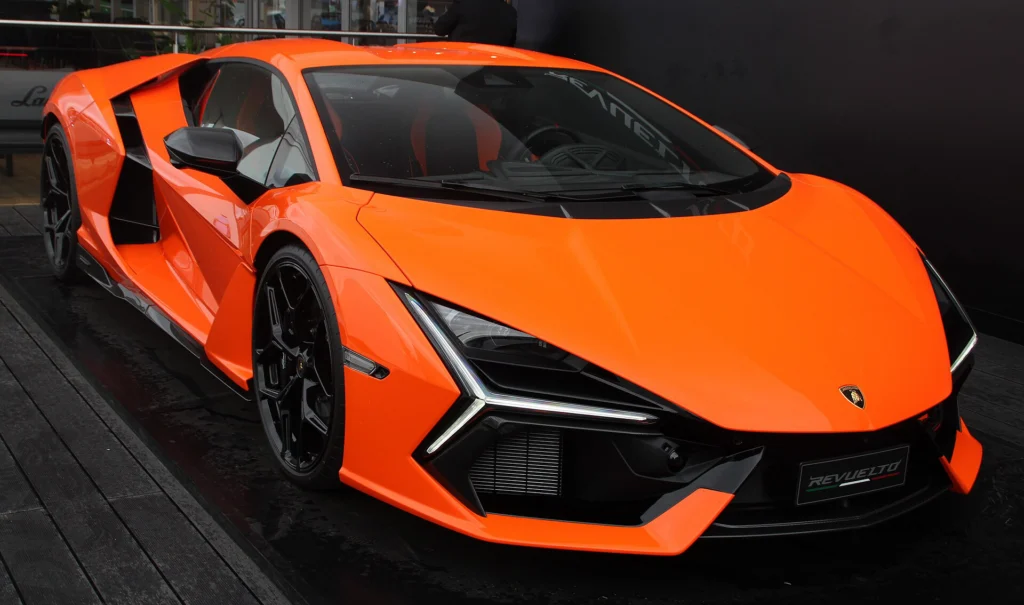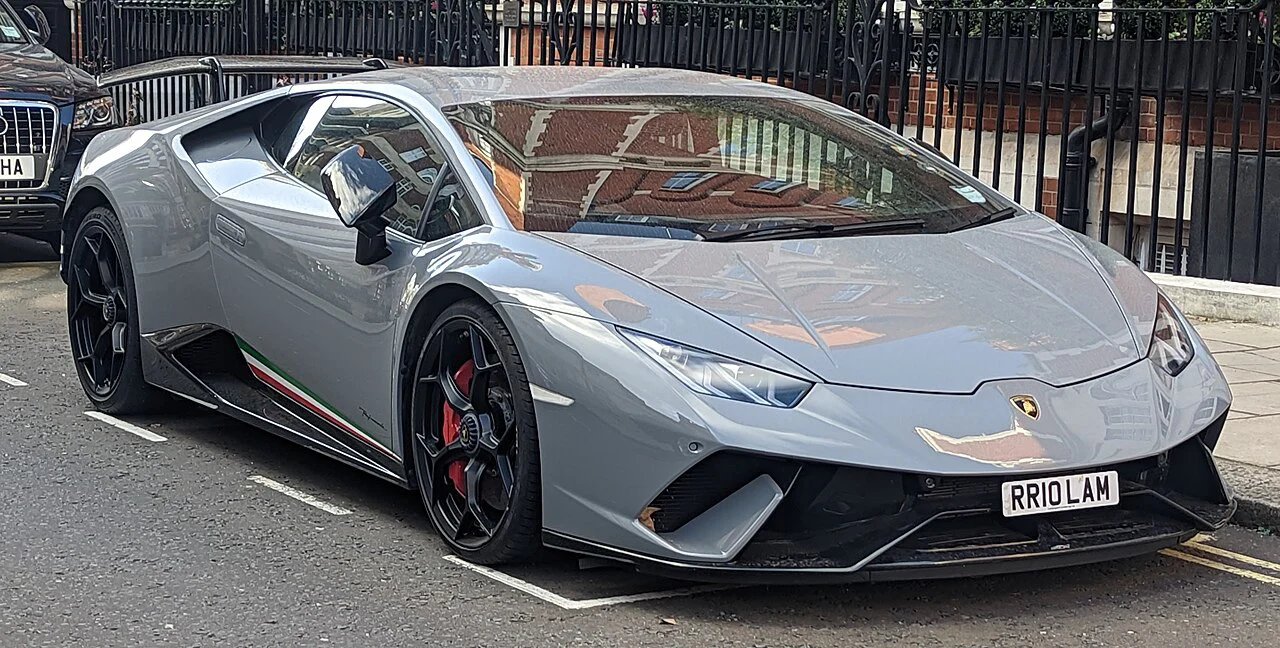
Crash a rented Lamborghini in New York and you’re probably on the hook for the car itself. Unless your own auto insurance, the rental company’s optional protection or a card policy covers the wreck, you’ll be paying for it. Who pays for injuries to others and damage to their vehicles, however, depends on a slew of other factors.
Fully Responsible for the Damage
For a long time New York law capped what a rental company could charge a renter for damage to the car at $100, no matter how dented it came back. A 2003 amendment removed the cap, so if you crash it you may be held fully responsible for the damage unless your personal auto policy, a credit card group policy or the optional vehicle protection the company can now sell covers it. The change only affects cars rented in New York. It brought the state’s law more in line with what other states’ laws allow.
But your liability still has its limits. A rental company cannot charge you more than the lesser of what it actually pays to repair the vehicle at a reasonable price and the car’s fair market value just before it got wrecked, minus whatever it gets for it when it’s sold as scrap. You’re also not on the hook for any of its ”loss of use” during the repairs or its administrative fees. Nor can it bill the damages as part of your rental agreement. New York law says it must present them to you on a separate bill.
One twist - the company can’t take a damage deposit or payment from you during the rental, or while you dispute the bill, until it gets a court judgment. It must also base its damage claim on a physical inspection of the car. If you drop it off after hours or by machine, the company has ten days to make its claims.
Rental Vehicle Endorsement
The law requires your own New York auto policy to cover your liability for damage to or loss of a rental car if you have fewer than five private passenger cars insured under your policy. The policy should have a separate rental vehicle endorsement. It covers your obligation to pay for any damage to or loss of the car, for any rental period that’s 30 days or less, for rentals in the U.S. or Canada. There’s no limit on how much a rental car endorsement must pay, so whatever a Lamborghini costs to repair should be covered even if it’s higher than your policy’s normal limits on damage you do to other people’s property. State regulators said the coverage applied when hubcaps were stolen from a rental car while the renter had it, and that same rule applies to policies issued through the New York Automobile Insurance Plan.
Without that endorsement, sometimes all you have is a premium credit card. But before counting on it to bail you out of that Lamborghini crash, check its terms. Some will exclude luxury cars, like that Lambo.
If you don’t have the benefit of a private auto policy’s rental car endorsement, maybe the rental company can offer you coverage through a damage waiver. New York’s daily price caps on collision damage waivers don’t apply to cars with an MSRP above $50,000, so a waiver price would not be capped in the case of that Lamborghini. On top of all that, a waiver may not cover you at all if you’ve been recklessly driving or let someone unauthorized take the wheel.
What Covers the People You Hurt
And if you hit people? New York Vehicle and Traffic Law 388 makes a car’s owner liable for injuries and damage caused by anyone driving it with permission. But the federal Graves Amendment shields a rental company from liability that comes only from owning the car, unless the company itself was negligent or committed a crime. A New York rental must include $25,000 of bodily injury liability for one injured person and $10,000 for other people’s property, which doesn’t cover the rental car itself. A crash in a Lamborghini can easily cost more, so the company’s optional supplemental liability protection, which usually provides $1 million, may be a good idea.
Get the insurance answers you need before you take the keys. Ask your own insurer to confirm your policy has the rental car endorsement. Read your credit card policy to see if it covers crash damage and excludes luxury cars. Once at the rental counter, decide if you need the company’s collision damage waiver and supplemental liability protection. Finally, when you drive off, drive carefully - both to get it back without a scratch and so any rental damage waiver you purchased won’t be voided for violating the rules.